
The real estate formulas that actually decide deals
Vocabulary is the gate, and math is the lock. You do not need calculus to buy real estate, but you do need about a dozen equations you can run in your head while a seller is still talking. Here they are, each spelled out in words, each worked with round numbers so the shape sticks.
From The REbuild — see all 456 pages →
The four that size every deal
$240,000 collected minus $96,000 to run the place is $144,000 of NOI. Debt service and big capital projects stay off this line; if a seller’s NOI has no management fee and no reserves, it is a marketing number, not a real one.
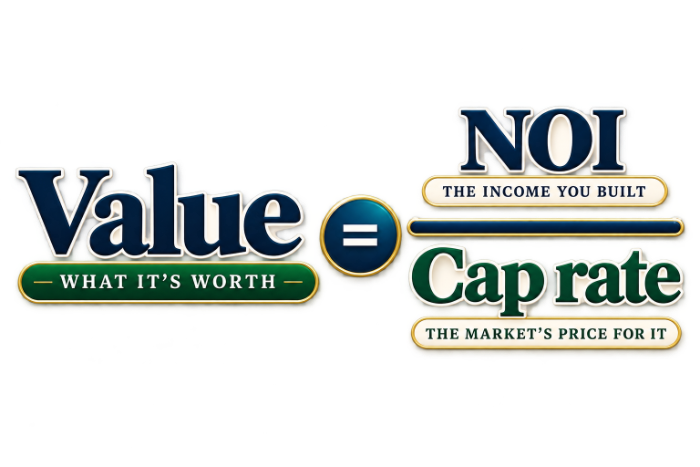
$144,000 on a $2,000,000 price is a 7.2 percent cap. Read it backward and it becomes a valuation tool: raise NOI to $180,000 at the same cap and the building is worth $2.5 million. That gap is the whole business.
$144,000 against $115,000 of payments is 1.25: the property earns a quarter more than it owes. Most lenders treat 1.20 to 1.25 as the floor, and the gap between your DSCR and theirs is your negotiating room.
$144,000 on a $1,500,000 loan is 9.6 percent. This is the return the bank earns if it takes the keys tomorrow, and on commercial deals it increasingly sizes the loan instead of DSCR. Ask which test bound yours.
The three that tell you what you earn
A $1,500,000 loan on a $2,000,000 building is 75 percent. Every point above the lender’s comfort line costs you rate, reserves, or a personal guarantee.
$29,000 of cash flow on $560,000 in is 5.2 percent. This is the only return number that answers what your own money did this year, leverage included.
$115,000 on a $1,500,000 loan is 7.7 percent. It bundles rate and amortization into one honest cost of debt, which is why a 30-year amortization at a higher rate can beat a 20-year at a lower one.
The three that keep you honest about occupancy
($96,000 + $115,000) ÷ $270,000 is 78 percent. Know this number before you close; it is your margin of survival, and it is why low-breakeven assets like storage sleep better in a downturn.
A building can be 95 percent physically full and 82 percent economically occupied once concessions, delinquency, and below-market legacy rents are counted. Physical occupancy flatters you. This one tells the truth.
$264,000 over 44,000 rentable square feet is $6.00. One number that catches price and fill together, which is why it is the score I read first on any storage facility.
The two for flips and forced value
A $400,000 after-repair value with $60,000 of rehab gives $220,000 as your ceiling. It is a screen, not a law: in tight markets seasoned operators work at 75 or 80 percent, but only with real comps and a real contractor bid.
$180,000 at a 7 percent cap is roughly $2.57 million. Commit this one to memory, because it converts every operational improvement into a dollar figure. Cut $10,000 of expense at a 7 cap and you created about $143,000 of value.
How to actually use them
Run them in order. NOI first, because everything downstream depends on it. Then cap rate to test the price, DSCR and debt yield to test the loan, break-even to test your survival, and cash-on-cash to decide whether your money had a better option. If a deal fails at NOI, nothing later saves it.
Then write down the walk-away number before you talk to anybody. A number decided in advance is a discipline. A number decided during a phone call is a hope.


