
How to read a T-12 and a rent roll without getting fooled
Two documents decide most deals: the T-12, which is the trailing twelve months of income and expenses, and the rent roll, which is the tenant-by-tenant snapshot. Sellers know you probably will not read them carefully. Read them carefully.
From The REbuild — see all 456 pages →
Step one: make the two documents agree
Add up the monthly rent on the rent roll, multiply by twelve, and compare that to the rental income line on the T-12. They will not match, and the gap is the education. That difference is concessions, delinquency, vacancy, and legacy rents nobody mentioned in the marketing package. If the gap is large and unexplained, you have found either an opportunity or a liar, and you need to know which before you go further.
Step two: read the last three months separately
Annualize the trailing three months and set it beside the full twelve. A property being dressed for sale almost always looks better recently: rents pushed, expenses deferred, a repair line that went quiet. If the recent quarter is dramatically stronger, ask what changed, and then verify the answer.
Step three: rebuild the expenses at your basis
This is where most seller NOI dies. Insert a market management fee even if the owner self-manages, because your time is not free and a lender will underwrite the fee anyway. Add honest reserves per unit or per square foot. Get a live insurance quote instead of using last year’s premium. And recalculate property taxes at your purchase price, not at the seller’s long-held assessed basis; in many states that single line moves the whole deal.
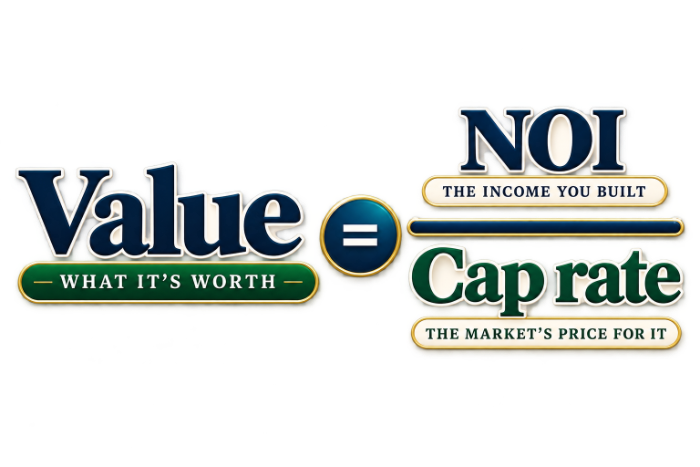
Sellers hand you an NOI with no management fee, no reserves, and stale taxes. Rebuild it and a 7 cap can quietly become a 5.5. Same building, different truth.
Step four: read the lease dates like a risk map
On the rent roll, look for a wall of leases expiring in the same sixty days, month-to-month tenants clustered in your best units, and free-rent concessions that hide the real achieved rate. In storage, look at how long tenants have been in place and when they last took a rate increase. Long-tenured tenants at old rates are the most reliable upside in the business.
Step five: verify with bank statements
Reports are opinions. Bank statements are facts. Ask for deposit records covering the trailing twelve, and reconcile the collections. Every takeover I have done found something: units marked vacant that were occupied, occupied units storing the seller’s own junk, locks with no ledger entry at all.
What this protects you from
Not a bad deal. A confident bad deal. The point of this work is that your offer comes from numbers you built, so when the seller pushes back you are not defending a spreadsheet you inherited. You are defending arithmetic you did.
The two documents that tell the truth
A seller’s offering memorandum is marketing. The trailing twelve months of operating statements and the current rent roll are evidence. Everything I decide about a property in the first hour comes from reading those two documents against each other and against the bank statements, and most of what I find is not in the brochure.
The T-12 tells you what happened. The rent roll tells you what is about to.
How I read a rent roll
Every unit on one page: size, current rate, street rate, move-in date, balance owed. Then I sort it three ways. By move-in date, to see how many tenants are on legacy rates from years ago and how large the gap to street is; that gap is the rate-increase opportunity. By balance, to find delinquency and how deep it runs. By rate against street, to find concessions that were never turned off. A rent roll with fifteen percent of tenants two months behind and thirty percent under street rate is a very different property from one that is clean, at the same physical occupancy.
The three lies I catch most
Occupancy counted physically when a tenth of the units are not paying. Expenses missing the owner’s own labor, which reappears as a manager’s salary the day you close. And revenue that includes a one-time insurance payout or a burst of auction proceeds that will not recur. None of these are usually fraud. They are how an owner who has stopped looking closely describes a property he has stopped looking at closely.
Where this goes in the process
Before the offer, not after. Sellers resist handing over the T-12 and rent roll until you are under contract, and I understand why, but a letter of intent with a short diligence window gets them in my hands before I am committed to a price. Reading them changes my number on roughly half the deals I look at, almost always downward, and the seller who provided clean documents gets a faster close as the reward for being organized.
A worked read, on a sixteen-unit
The T-12 on the Michigan building showed collected rent climbing gently across the year and an expense ratio around thirty-one percent. Two things jumped out. First, no management line at all; the owner ran it himself, which meant a real manager would add three to four points of expense on day one. Second, insurance had renewed in month eight at nearly double the prior premium, so the twelve-month total understated the run rate by roughly ten thousand dollars. Normalized, the expense ratio was closer to forty, and NOI dropped by a fifth. My offer dropped with it, and the seller, to his credit, understood why once I walked him through the two lines.
The rent roll told the other half. Six of sixteen tenants had moved in more than four years earlier and sat eighteen to twenty-five percent under street. Two units showed balances over sixty days. One unit was marked occupied at zero rent, which turned out to be the owner’s storage. That is not a ninety-four percent occupied building. It is an eighty-one percent economic building with a clear path back to ninety-plus, and that path was worth more to me than the brochure number.
The questions the documents raise
Every anomaly becomes a question for the seller, and the way they answer tells you almost as much as the numbers. Why did insurance double? Was there a claim? Why is unit twelve at zero? How long has unit four been behind, and what has been done about it? Sellers who answer plainly tend to have clean buildings with a few honest problems. Sellers who get vague about a rent roll are usually describing a building they have stopped managing, and that is either the opportunity or the warning, depending on the price.
Build the habit
Read these two documents on every deal you look at, including the ones you will not buy. The pattern recognition compounds faster than any course. After fifty rent rolls you can spot the legacy-rate cluster in ten seconds, and after fifty T-12s the missing expense line stands out like a typo. That speed is what lets the thirty-second screen be honest, because the instinct behind it was trained on real paper.
What to ask for, and in what form
Ask for the T-12 as a monthly spreadsheet, not a summary PDF, so you can see each line move. Ask for the rent roll as of a specific date, exported from the management software, not retyped. Ask for twelve months of bank statements for the operating account. And ask for the prior year’s tax return for the property, because the numbers a seller reports to the IRS tend to be more conservative than the numbers in the brochure, and the gap between them is instructive.
If any of those four is refused, the deal is not dead, but the price should reflect the uncertainty. I have paid less for buildings with messy records and made money on them, because the mess was the discount. What I will not do is pay a clean-records price for a property that will not show me its records.
A short list of things that are not in either document
Deferred maintenance, which is on the roof and in the mechanical room, not on the statement. Pending rate increases the seller has already noticed the market will bear. Competitors under construction down the road. The manager’s intention to quit the week you close. The T-12 and rent roll are where underwriting starts, and the property walk, the competitor drive, and the manager conversation are where it finishes. Read the paper first so you know what to look for when you get there.
The twenty-minute version
If you only have twenty minutes: open the T-12, look at the last three months against the first three and note the direction. Find the expense lines that are missing and add them at market. Open the rent roll, sort by move-in date, and count how many tenants are more than three years in and under street rate. Sort by balance and count anyone over sixty days. Those four looks, before you have read a single word of the brochure, tell you whether the property is a lazy asset with upside or a clean asset at full price, and that is the only distinction that matters before the offer.


